INTRODUCTION
Financial literacy has become one of the most extensively studied topics in the financial research landscape, with researchers increasingly focused on understanding how financial knowledge translates into investment behavior. A comprehensive bibliometric analysis covering research from 1981 to 2024 reveals that financial literacy is now understood as a multidimensional concept influenced by demographic, socio-economic, psychological, financial, societal, Islamic, and technological factors . This research has significant implications, as financial literacy is considered an essential attribute for individuals and businesses to make optimal financial decisions .
In 2026, the research landscape for financial literacy and investment decisions has undergone a remarkable transformation. What was once a latent field of study has entered an exponential growth stage, predominantly driven by emerging economies such as India, Indonesia, and Pakistan . This growth reflects both the increasing complexity of financial markets and the recognition that financial literacy is a critical tool for economic participation.
This guide presents a bibliometric overview of research on financial literacy and investment decision-making, examining growth trends, thematic evolution, influential contributors, and future research avenues.
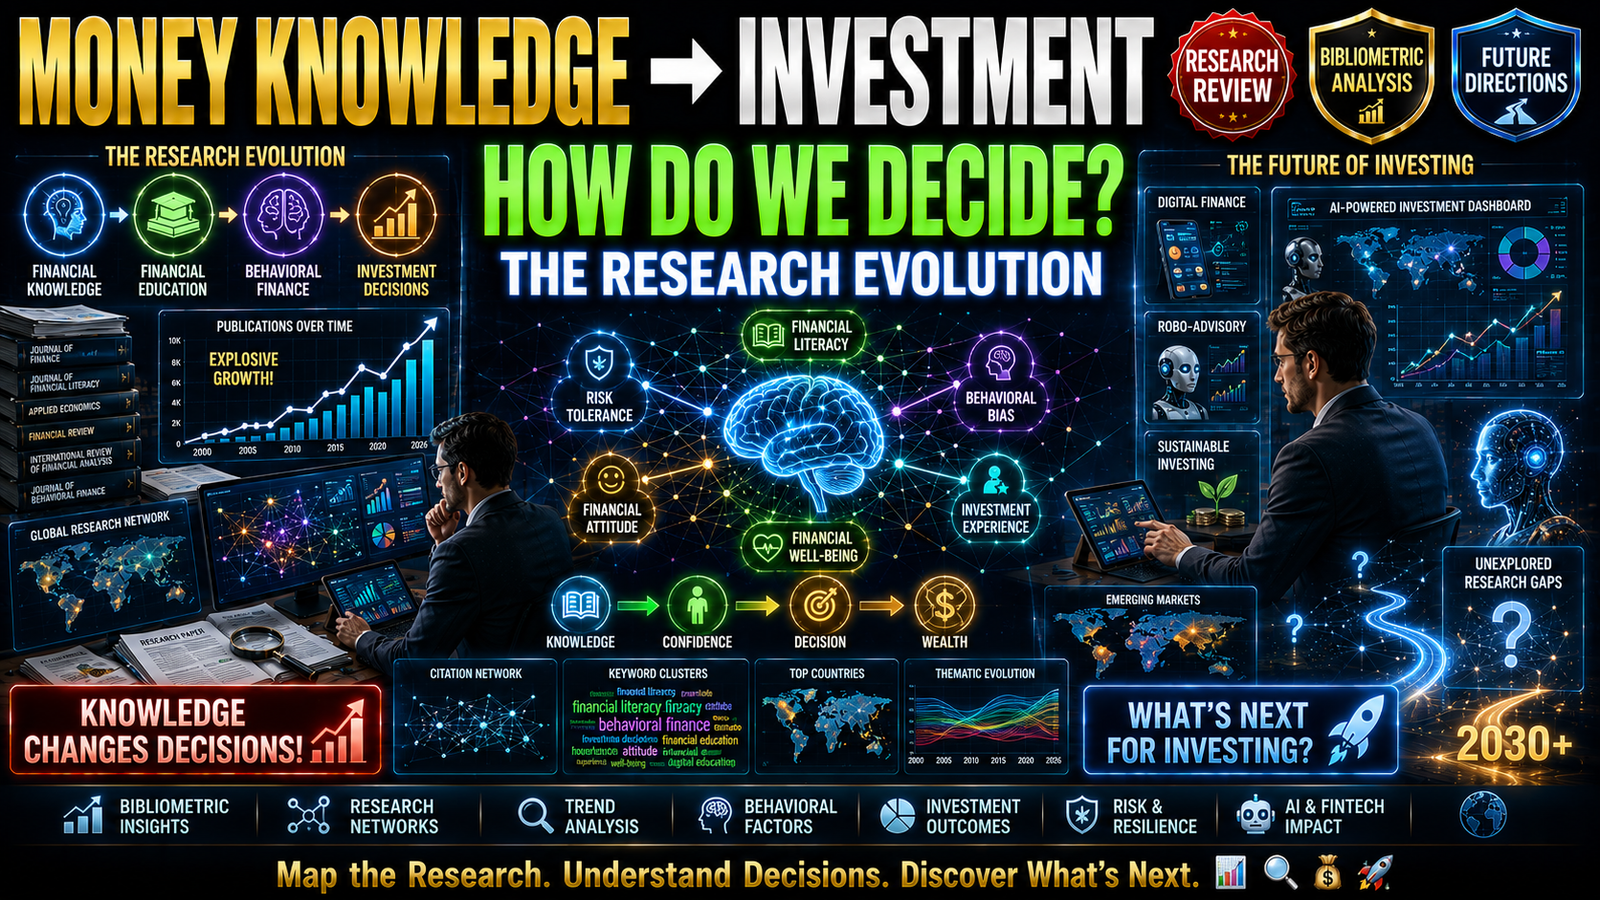
THE EVOLUTION OF FINANCIAL LITERACY RESEARCH
Three Phases of Evolution
Bibliometric analysis of financial literacy and investment decision-making research reveals three clear evolutionary phases :
Phase 1: Conceptual Foundation Phase (pre-2020): Early research focused on establishing financial literacy as a distinct field of study. Researchers worked to define the concept, develop measurement tools, and understand the relationship between basic financial knowledge and decision-making outcomes. This phase established the foundational understanding that financial literacy is a multidimensional concept .
Phase 2: Behavioural Finance Phase (2020–2024): Research shifted toward understanding psychological factors and cognitive biases in financial decision-making. Researchers explored how overconfidence, loss aversion, and other behavioural biases affect investment choices. This phase recognized that financial knowledge alone is insufficient—attitudes and behaviours matter equally.
Phase 3: Cognitive Process-Oriented Phase (post-2024): The current phase integrates digital financial tools, mitigates cognitive biases, and focuses on wealth maximization . This represents a significant paradigm shift from traditional financial knowledge toward digital financial capability .
The Shift to Exponential Growth
The research field has moved from a latent state to exponential growth, predominantly driven by emerging economies . This growth reflects:
- Increasing financial complexity in developing markets
- Growing recognition of financial literacy as a policy priority
- Rapid digitisation of financial services in emerging economies
- Post-pandemic focus on financial resilience and household finance
DETERMINANTS OF FINANCIAL LITERACY
A Multidimensional Framework
Financial literacy is now understood as a multidimensional concept influenced by seven distinct categories of factors :
- Demographic Factors: Age, gender, education level, income, and employment status
- Socio-economic Factors: Social class, economic environment, and access to resources
- Psychological Factors: Self-confidence, financial attitudes, and risk tolerance
- Financial Factors: Prior financial experience and exposure to financial products
- Societal Factors: Cultural norms and social influences
- Islamic Factors: Religious perspectives on financial matters
- Technological Factors: Digital literacy and access to financial technology
Research Gaps
While demographic and socio-economic factors are widely used in financial literacy research, psychological, financial, societal, and Islamic factors have received less attention . The integration of technology into financial markets has recently drawn interest in the technological facet of financial literacy, suggesting that digital financial literacy may deserve further investigation .
DIGITAL FINANCE AND FINANCIAL LITERACY
A Paradigm Shift
A comprehensive bibliometric analysis covering 970 Scopus-indexed journal articles from 2008 to 2026 reveals a significant paradigm shift from traditional financial knowledge toward digital financial capability . This shift emphasizes the importance of technological competencies in shaping financial behaviour in an increasingly digitised financial ecosystem .
Dominant Research Themes
The analysis identifies financial technology (FinTech) and structural equation modelling as dominant motor themes, reflecting the field’s methodological and technological advancement . In contrast, financial literacy, financial inclusion, and digital financial inclusion emerge as foundational yet underdeveloped themes, indicating the need for deeper theoretical integration .
The Role of Emerging Economies
The growing prominence of emerging economies in knowledge production underscores the global relevance of digital financial inclusion . Research from emerging economies has become increasingly influential, with institutions in India, Indonesia, and Pakistan leading recent growth in publication output .
SOCIAL MEDIA AND FINANCIAL LITERACY
Growth of Research
Research on social media and financial literacy has been growing since 2001, with a gradual upward trend in scientific production. Particularly after 2008, the scientific production gained significant attention from researchers globally .
Key Contributions
The most productive countries are the USA and China, with Sustainability (Switzerland) as the most productive source journal . Post-Covid-19 pandemic, more attention is being paid to finances, especially financial wellbeing and household finance . Several authors have worked together, making it a collaborative research area .
Practical Implications
The research guides policymakers, financial institutions, and banks in using social media for promoting financial literacy . However, researchers note that financial influencers operating outside traditional regulatory frameworks may spread misleading or biased information . Regulators are increasingly developing frameworks to regulate financial influencers and protect retail investors .
FINANCIAL LITERACY IN EMERGING ECONOMIES
Africa as a Research Frontier
A retrospective investigation of financial literacy studies in the African context, based on 336 publications indexed in the Scopus database, shows recent and rapid growth in the financial literacy literature . Human development is a dominant research theme, but economics and business management are emerging themes with the potential to become fully settled .
SMEs Financial Literacy Research
Research on financial literacy among small and medium-sized enterprises (SMEs) has gained significant attention. A bibliometric analysis of 195 articles published between 2021 and 2024 identifies key research themes including :
- Empowerment through financial literacy
- SMEs development, planning, and preparedness
- Addressing gaps in financial inclusion and personal finance behaviour
- Addressing disparities and enhancing education
RESEARCH GAPS AND FUTURE DIRECTIONS
Critical Research Gaps
Bibliometric analyses consistently identify several critical research gaps :
- Behavioural Dimensions: Psychological factors driving financial decision-making remain under-explored
- Digital Inclusion Disparities: Digital access and skills affect financial literacy, but require deeper investigation
- Regulatory Frameworks: Financial regulations for digital finance need more research attention
- Interdisciplinary Exploration: More research is needed on AI, machine learning, and financial literacy
Future Research Questions
Based on the evidence, future research should address :
- How can digital financial tools be leveraged to mitigate cognitive biases?
- What interventions effectively build digital financial capability?
- How does financial literacy differ across emerging and developed economies?
- What role do AI and machine learning play in financial literacy and decision-making?
- How can financial education be delivered effectively in underserved populations?
FREQUENTLY ASKED QUESTIONS
What are the main phases of financial literacy research evolution?
Research has evolved through three phases: conceptual foundation (pre-2020), behavioural finance (2020–2024), and cognitive process-oriented (post-2024), which integrates digital financial tools .
What factors influence financial literacy?
Financial literacy is influenced by demographic, socio-economic, psychological, financial, societal, Islamic, and technological factors .
How is digital finance changing financial literacy research?
Research is shifting from traditional financial knowledge toward digital financial capability, emphasising the importance of technological competencies in shaping financial behaviour .
Which countries are leading financial literacy research?
Emerging economies such as India, Indonesia, and Pakistan are driving recent growth, while the USA and China lead in social media and financial literacy research .
What are the under-researched areas in financial literacy?
Key gaps include behavioural dimensions, digital inclusion disparities, regulatory frameworks, and interdisciplinary exploration .
How does financial literacy research guide policy?
Research provides evidence for policymakers, financial institutions, and banks in promoting financial literacy through various channels, including social media and digital platforms .
CONCLUSION
Financial literacy research has evolved dramatically, from a latent field of study to an exponential growth area, driven predominantly by emerging economies. The field has shifted from conceptual foundations through behavioural finance to a cognitive process-oriented approach integrating digital financial tools.
The research reveals that financial literacy is a multidimensional concept influenced by demographic, socio-economic, psychological, financial, societal, Islamic, and technological factors. While demographic and socio-economic factors are widely studied, psychological, financial, societal, and Islamic factors have received less attention.
The integration of technology into financial markets has drawn recent research interest, particularly in FinTech and digital financial literacy. The growing prominence of emerging economies in knowledge production underscores the global relevance of digital financial inclusion.
Critical research gaps remain in behavioural dimensions, digital inclusion disparities, regulatory frameworks, and interdisciplinary exploration. Future research should leverage AI, machine learning, and digital tools to better understand and enhance financial literacy.
The implication for policymakers and educators is clear: as financial literacy research evolves, financial education must adapt to the digital age. The demand for accessible, trustworthy financial education has never been greater, and the opportunity to meet that demand has never been clearer.