INTRODUCTION
What is a company truly worth? This is one of the most important questions in finance, and the discounted cash flow (DCF) method is arguably the most rigorous way to answer it. Warren Buffett, one of the world’s most successful investors, has long emphasized the importance of DCF analysis in making investment decisions.
In simple terms, discounted cash flow is a valuation method that estimates the value of an investment based on its expected future cash flows. The core idea is that a dollar today is worth more than a dollar tomorrow because money can be invested today to earn a return. By discounting future cash flows back to their present value, DCF provides an intrinsic value that can be compared to the current market price.
In 2026, DCF analysis remains a cornerstone of corporate finance, investment banking, equity research, and private equity. Whether you are evaluating a stock, a business acquisition, a real estate project, or a capital investment, understanding DCF is essential.
In this complete guide, we will walk you through everything you need to know about discounted cash flow analysis. You will learn what DCF is, why it matters, the formula and components, how to calculate it step by step, common mistakes, and practical examples. By the end, you will have the confidence to perform your own DCF valuations.
WHAT IS DISCOUNTED CASH FLOW (DCF)?
Discounted cash flow (DCF) is a financial valuation method that uses projected future cash flows and discounts them back to the present using a required rate of return. The fundamental principle behind DCF is the time value of money – the concept that money available today is worth more than the same amount in the future due to its potential earning capacity.
The DCF method calculates the present value of all expected future cash flows from an investment, business, or project. If the present value of these cash flows exceeds the current cost of the investment, the investment is considered attractive. If it is lower, the investment is overvalued.
Some key characteristics of DCF analysis:
- Based on actual cash flows, not accounting earnings
- Incorporates the time value of money through discounting
- Provides an intrinsic value independent of market sentiment
- Widely used in mergers and acquisitions, capital budgeting, and stock valuation
- Requires careful forecasting and assumptions
DCF is considered one of the most theoretically sound valuation methods because it focuses on cash generation rather than accounting metrics like earnings per share or book value. However, its accuracy depends heavily on the quality of the underlying assumptions.
WHY DISCOUNTED CASH FLOW MATTERS IN 2026
In 2026, the importance of discounted cash flow analysis has only grown. Several factors make DCF particularly relevant in today’s financial environment.
First, interest rates have stabilized after years of volatility, but they remain higher than the near-zero levels seen in the previous decade. This makes the discount rate, a critical component of DCF, more impactful than ever. Small changes in interest rates can significantly alter present values, making accurate assumptions essential.
Second, market volatility continues to create pricing inefficiencies. Stocks, bonds, and private companies often trade at prices that do not reflect their fundamentals. DCF provides a disciplined framework to identify undervalued or overvalued assets.
Third, the rise of environmental, social, and governance (ESG) investing has increased demand for long-term cash flow projections. Companies with sustainable business models often trade at premiums, and DCF helps quantify that value.
Fourth, DCF is increasingly applied to new asset classes, including cryptocurrencies, digital assets, and intellectual property. While traditional DCF was designed for tangible assets, adaptations are being developed for these emerging areas.
Fifth, regulators and accounting standard-setters are placing greater emphasis on fair value measurements, making DCF a standard tool for financial reporting, impairment testing, and purchase price allocation.
THE DCF FORMULA AND ITS COMPONENTS
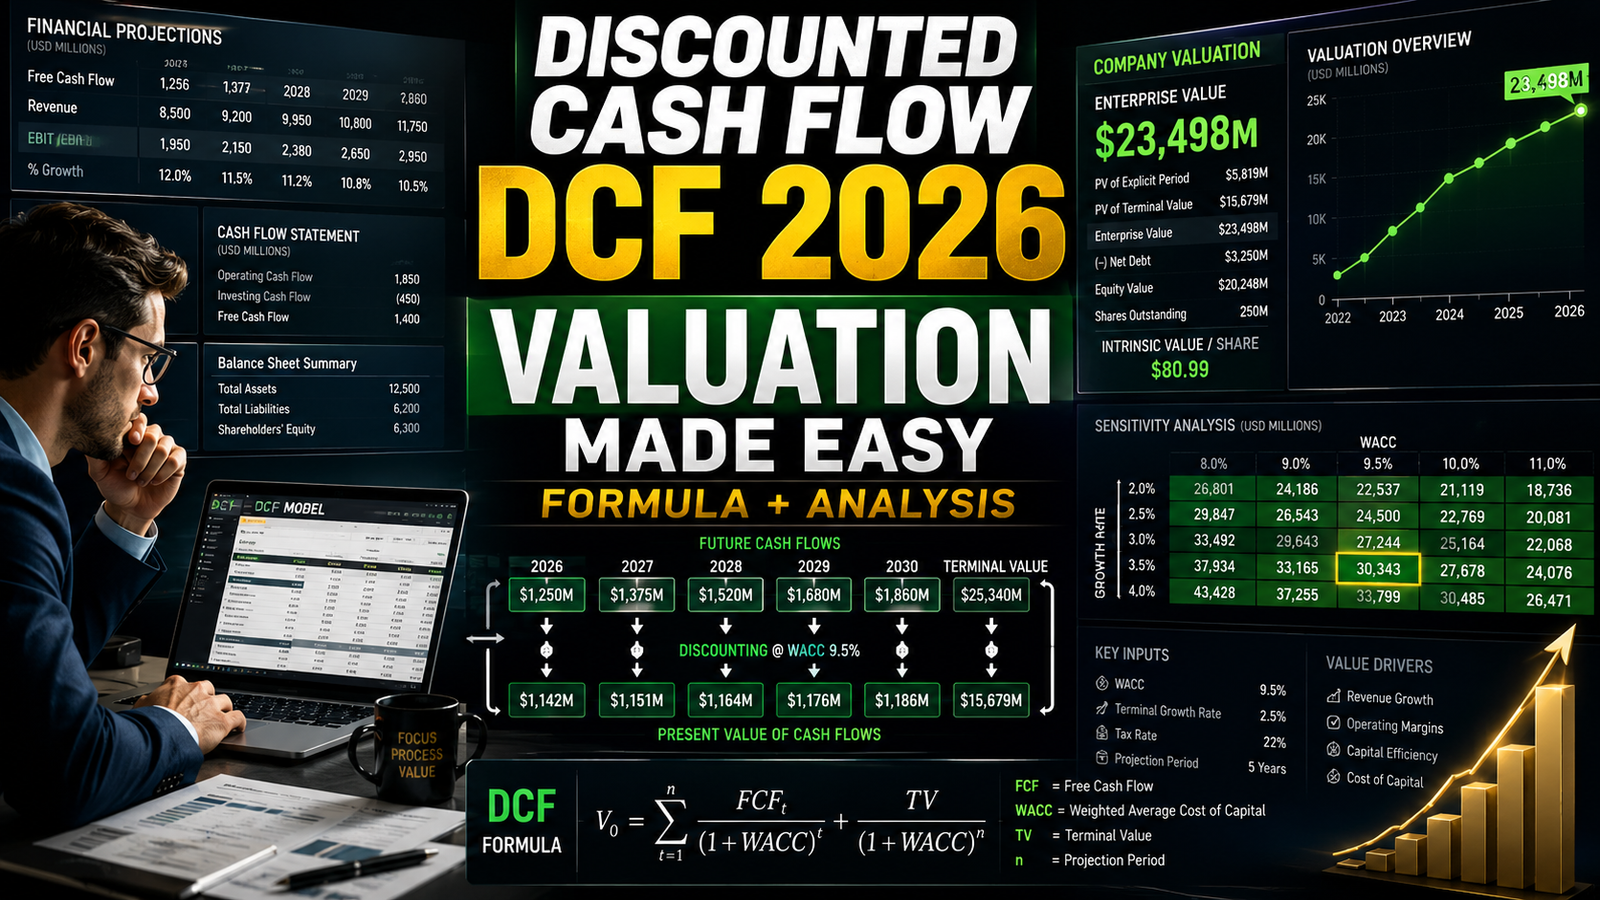
The DCF formula can be expressed as:
DCF = CF₁ / (1+r)¹ + CF₂ / (1+r)² + CF₃ / (1+r)³ + … + CFₙ / (1+r)ⁿ + Terminal Value / (1+r)ⁿ
Where:
- CF₁, CF₂, …, CFₙ = Expected future cash flows for each period
- r = Discount rate (required rate of return, often the weighted average cost of capital or WACC)
- n = Number of periods
- Terminal Value = Value of the investment at the end of the forecast period
The formula can be broken down into four main components:
1. Free Cash Flows (FCF)
Free cash flow is the cash generated by a business after accounting for capital expenditures necessary to maintain or expand its asset base. It represents the cash available to all investors – both debt and equity holders. Two common measures are:
- Free Cash Flow to the Firm (FCFF): Cash available to all capital providers
- Free Cash Flow to Equity (FCFE): Cash available to equity shareholders only
2. Discount Rate (r)
The discount rate reflects the riskiness of the future cash flows. For a company, the most common discount rate is the weighted average cost of capital (WACC), which blends the cost of equity and the cost of debt.
For a project or investment, the discount rate is the required rate of return that compensates for the risk involved. Higher risk investments require higher discount rates, which reduce the present value of future cash flows.
3. Forecast Period
The forecast period is the number of years for which cash flows are explicitly projected. Typically, this ranges from 5 to 10 years. Beyond this period, a terminal value is calculated to capture the remaining value.
4. Terminal Value
Terminal value represents the value of the investment at the end of the forecast period. It often accounts for 60% to 80% of the total DCF value. Two common methods for calculating terminal value are:
- Perpetuity Growth Method: Assumes cash flows grow at a constant rate forever
- Exit Multiple Method: Applies a valuation multiple (like EV/EBITDA) to the final year’s financials
HOW TO CALCULATE DCF – STEP BY STEP
Performing a discounted cash flow analysis involves eight systematic steps. Each step requires careful thought, data, and assumptions.
Step 1: Project Free Cash Flows
Begin by forecasting the company’s financial statements – income statement, balance sheet, and cash flow statement – for the next 5 to 10 years. Calculate free cash flow for each year using the formula:
Free Cash Flow = Operating Cash Flow – Capital Expenditures
For FCFF specifically:
FCFF = EBIT × (1 – Tax Rate) + Depreciation & Amortization – Capital Expenditures – Change in Working Capital
Use historical data, industry trends, management guidance, and economic forecasts to build realistic projections. Avoid overly optimistic or pessimistic assumptions.
Step 2: Determine the Discount Rate (WACC)
Calculate the weighted average cost of capital. WACC is the weighted average of the cost of equity and the after-tax cost of debt, weighted by their respective market values.
WACC = (E/V × Re) + (D/V × Rd × (1 – T))
Where:
- E = Market value of equity
- D = Market value of debt
- V = E + D
- Re = Cost of equity
- Rd = Cost of debt
- T = Corporate tax rate
The cost of equity is typically calculated using the Capital Asset Pricing Model (CAPM):
Re = Risk-Free Rate + Beta × (Market Risk Premium)
Step 3: Calculate the Present Value of Projected Cash Flows
Discount each year’s projected free cash flow back to the present using the WACC.
Present Value of Cash Flow = Cash Flow / (1 + WACC)^n
Where n is the number of years into the future.
Step 4: Estimate the Terminal Value
Calculate the terminal value at the end of the forecast period using the perpetuity growth method:
Terminal Value = (Final Year Cash Flow × (1 + g)) / (WACC – g)
Where g is the assumed long-term growth rate, typically between 2% and 3%, in line with long-term GDP growth.
Alternatively, use the exit multiple method:
Terminal Value = Final Year EBITDA × Industry Comparable Multiple
Step 5: Discount the Terminal Value
Discount the terminal value back to the present using the same WACC:
Present Value of Terminal Value = Terminal Value / (1 + WACC)^n
Step 6: Sum Present Values
Add the present value of projected cash flows and the present value of the terminal value to arrive at the total enterprise value.
Total Enterprise Value = Sum of Discounted Cash Flows + Discounted Terminal Value
Step 7: Adjust for Non-Operating Items
Adjust the enterprise value by adding excess cash and other non-operating assets and subtracting debt, minority interests, and preferred equity. This yields the equity value.
Equity Value = Enterprise Value + Excess Cash – Debt – Minority Interests – Preferred Equity
Step 8: Calculate Per-Share Value
Divide the equity value by the number of outstanding shares to arrive at the intrinsic value per share.
Intrinsic Value Per Share = Equity Value / Number of Shares Outstanding
Compare this to the current market price to determine whether the investment is undervalued or overvalued.
KEY BENEFITS OF DCF ANALYSIS
DCF analysis offers several distinct advantages for investors, analysts, and business leaders.
- Based on Cash Flows: Unlike earnings, cash flows are harder to manipulate through accounting choices. DCF focuses on actual cash generation.
- Incorporates Time Value of Money: DCF recognizes that money today is worth more than money tomorrow.
- Provides Intrinsic Value: DCF gives a fair value that is independent of market sentiment and current stock price.
- Applicable to Multiple Scenarios: DCF can be used for public companies, private businesses, real estate, projects, and even intellectual property.
- Encourages Rigorous Thinking: The process forces analysts to examine assumptions about growth, margins, investment needs, and risk.
- Widely Accepted: DCF is a standard tool used by investment banks, private equity firms, corporate finance departments, and valuation professionals globally.
POTENTIAL RISKS AND DRAWBACKS
While DCF is powerful, it is also sensitive to assumptions and has several limitations.
- Forecast Uncertainty: Small changes in assumptions can lead to vastly different valuations. DCF is often referred to as “garbage in, garbage out.”
- Sensitivity to Discount Rate: A 1% change in WACC can change the valuation by 10% to 20% or more.
- Terminal Value Dominance: Terminal value often accounts for a large portion of the total value, making long-term assumptions critical.
- Difficulty Forecasting Long-Term Growth: Predicting growth rates beyond 5 years is challenging, especially for volatile industries.
- Not Suitable for All Companies: DCF is less reliable for companies with negative cash flows, high cyclicality, or limited historical data.
- Assumes Efficient Markets: DCF assumes that markets eventually reflect fundamental value, which may not always hold.
COMMON MISTAKES TO AVOID
Avoid these common errors to improve the accuracy and credibility of your DCF analysis.
Mistake 1: Overly Optimistic Growth Assumptions
Many analysts project growth rates that are unsustainably high. Be realistic and align growth with industry averages, GDP growth, and historical performance.
Mistake 2: Mismatched Discount Rate and Cash Flows
If you are projecting FCFF, use WACC. If you are projecting FCFE, use the cost of equity. Mixing these leads to incorrect valuations.
Mistake 3: Ignoring Capital Expenditures
DCF valuation requires free cash flow, which deducts capital expenditures. Ignoring CapEx overstates cash flow and inflates value.
Mistake 4: Forgetting to Adjust for Non-Operating Items
Failing to add excess cash or subtract debt and other liabilities leads to an inaccurate equity value.
Mistake 5: Using an Inconsistent Forecast Period
Ensure the forecast period covers at least one full business cycle (typically 5 to 10 years). Shorter periods can misrepresent value.
Mistake 6: Not Performing Sensitivity Analysis
Always test how changes in key assumptions affect the final valuation. This provides a range of values and highlights the most critical assumptions.
REAL-WORLD EXAMPLE
Let us walk through a simplified DCF example for a fictional company, ABC Manufacturing.
Assumptions:
- Forecast period: 5 years
- WACC: 10%
- Perpetuity growth rate: 2.5%
- Outstanding shares: 1,000,000
- Excess cash: $5 million
- Debt: $15 million
Projected Free Cash Flows (FCFF):
- Year 1: $4.0 million
- Year 2: $4.5 million
- Year 3: $5.0 million
- Year 4: $5.5 million
- Year 5: $6.0 million
Discounted Cash Flows:
- Year 1: $4.0 / (1.10)^1 = $3.64 million
- Year 2: $4.5 / (1.10)^2 = $3.72 million
- Year 3: $5.0 / (1.10)^3 = $3.76 million
- Year 4: $5.5 / (1.10)^4 = $3.76 million
- Year 5: $6.0 / (1.10)^5 = $3.73 million
Sum of Discounted Cash Flows:
$3.64 + $3.72 + $3.76 + $3.76 + $3.73 = $18.61 million
Terminal Value:
Terminal Value = ($6.0 × 1.025) / (0.10 – 0.025) = $6.15 / 0.075 = $82.0 million
Discounted Terminal Value:
$82.0 / (1.10)^5 = $82.0 / 1.6105 = $50.92 million
Enterprise Value:
$18.61 million + $50.92 million = $69.53 million
Equity Value:
$69.53 million + $5 million excess cash – $15 million debt = $59.53 million
Intrinsic Value Per Share:
$59.53 million / 1,000,000 shares = $59.53 per share
If ABC Manufacturing’s current stock price is $50 per share, the DCF suggests the stock is undervalued by approximately 19%.
FREQUENTLY ASKED QUESTIONS
What is a good discount rate for DCF?
A good discount rate depends on the risk of the investment. For established companies, WACC typically ranges from 8% to 12%. For startups or high-growth companies, rates can be 15% to 25% or higher.
Is DCF better than comparable company analysis?
DCF and comparable company analysis serve different purposes. DCF provides an intrinsic value based on fundamentals. Comparables provide a market-based value based on what similar companies are trading for. Both should be used together for a comprehensive valuation.
How do you calculate terminal value?
Terminal value is calculated using the perpetuity growth method: Terminal Value = (Final Year Cash Flow × (1 + g)) / (WACC – g), where g is the long-term growth rate. Alternatively, use the exit multiple method.
What is the difference between FCFF and FCFE?
FCFF is free cash flow to the firm, available to all capital providers (debt and equity). FCFE is free cash flow to equity, available only to equity shareholders. FCFF is discounted by WACC, while FCFE is discounted by the cost of equity.
Can DCF be used for startups?
Yes, but it is more challenging due to limited financial history and higher uncertainty. Assumptions must be conservative, and sensitivity analysis is critical. Higher discount rates should be used to reflect the elevated risk.
How sensitive is DCF to growth assumptions?
DCF is highly sensitive to growth assumptions. A 1% change in the terminal growth rate can alter valuation by 10% to 20%. Always perform sensitivity analysis to understand the range of possible values.
What is the difference between DCF and net present value (NPV)?
NPV is the difference between the present value of cash inflows and the present value of cash outflows. It is typically used for project or investment decisions. DCF is the broader valuation method that calculates the total present value of all future cash flows, often for an entire business.
CONCLUSION
Discounted cash flow analysis is one of the most powerful and widely used valuation methods in finance. It provides a rigorous, cash-flow-based framework to determine the intrinsic value of a company, project, or investment. By accounting for the time value of money and requiring detailed forecasting, DCF forces analysts to think critically about a business’s fundamentals.
However, DCF is only as good as the assumptions behind it. Small changes in growth rates, discount rates, or cash flow projections can lead to vastly different valuations. That is why sensitivity analysis, realistic assumptions, and cross-checking with other valuation methods are essential.
Whether you are an equity research analyst, an investment banker, a corporate finance professional, or an individual investor, mastering DCF analysis will give you a significant edge in making informed financial decisions.
Start practicing with real companies, refine your forecasting skills, and always challenge your assumptions. Over time, DCF will become an invaluable tool in your financial toolkit.
Explore more valuation guides and financial analysis articles on Akashhelps.com.
Disclaimer: This content is for informational and educational purposes only and does not constitute professional financial advice. Always consult with a certified financial advisor or investment professional before making investment decisions. Akashhelps.com is not responsible for any losses or damages resulting from the use of this information.
Author Bio: This guide was written by the finance content team at Akashhelps.com, with extensive experience in valuation, corporate finance, and investment analysis. We are committed to providing accessible, accurate, and actionable financial education.
Last reviewed: August 2026
Sources:
- McKinsey & Company – Valuation: Measuring and Managing the Value of Companies
- Damodaran Online – DCF Valuation Resources
- Financial Accounting Standards Board (FASB) – Fair Value Measurement
- U.S. Securities and Exchange Commission – EDGAR Company Filings
- Federal Reserve – Interest Rate Data