INTRODUCTION
Between 2008 and 2026, financial literacy research underwent a dramatic transformation. What began as a niche academic pursuit focused on measuring basic financial knowledge has evolved into a global, interdisciplinary field examining digital finance, behavioral economics, and financial inclusion. The drivers of this shift are clear: the 2008 financial crisis, the COVID-19 pandemic, and the rapid digitization of financial services have all forced researchers and policymakers to ask a urgent question: do people actually understand the financial tools available to them?
In 2026, the answer is mixed. Academic research is flourishing, with over 6,300 documents published on financial literacy since 1963 and annual growth rates accelerating post-2020. Yet national surveys show financial literacy at its lowest point in a decade. Meanwhile, search data reveals a world more financially curious—and more confused—than ever before.
This guide presents a comprehensive bibliometric analysis of financial literacy research, combined with real-world search behavior data, to reveal the trends, gaps, and opportunities in financial education today.
THE STATE OF FINANCIAL LITERACY RESEARCH
The Scale of the Research Landscape
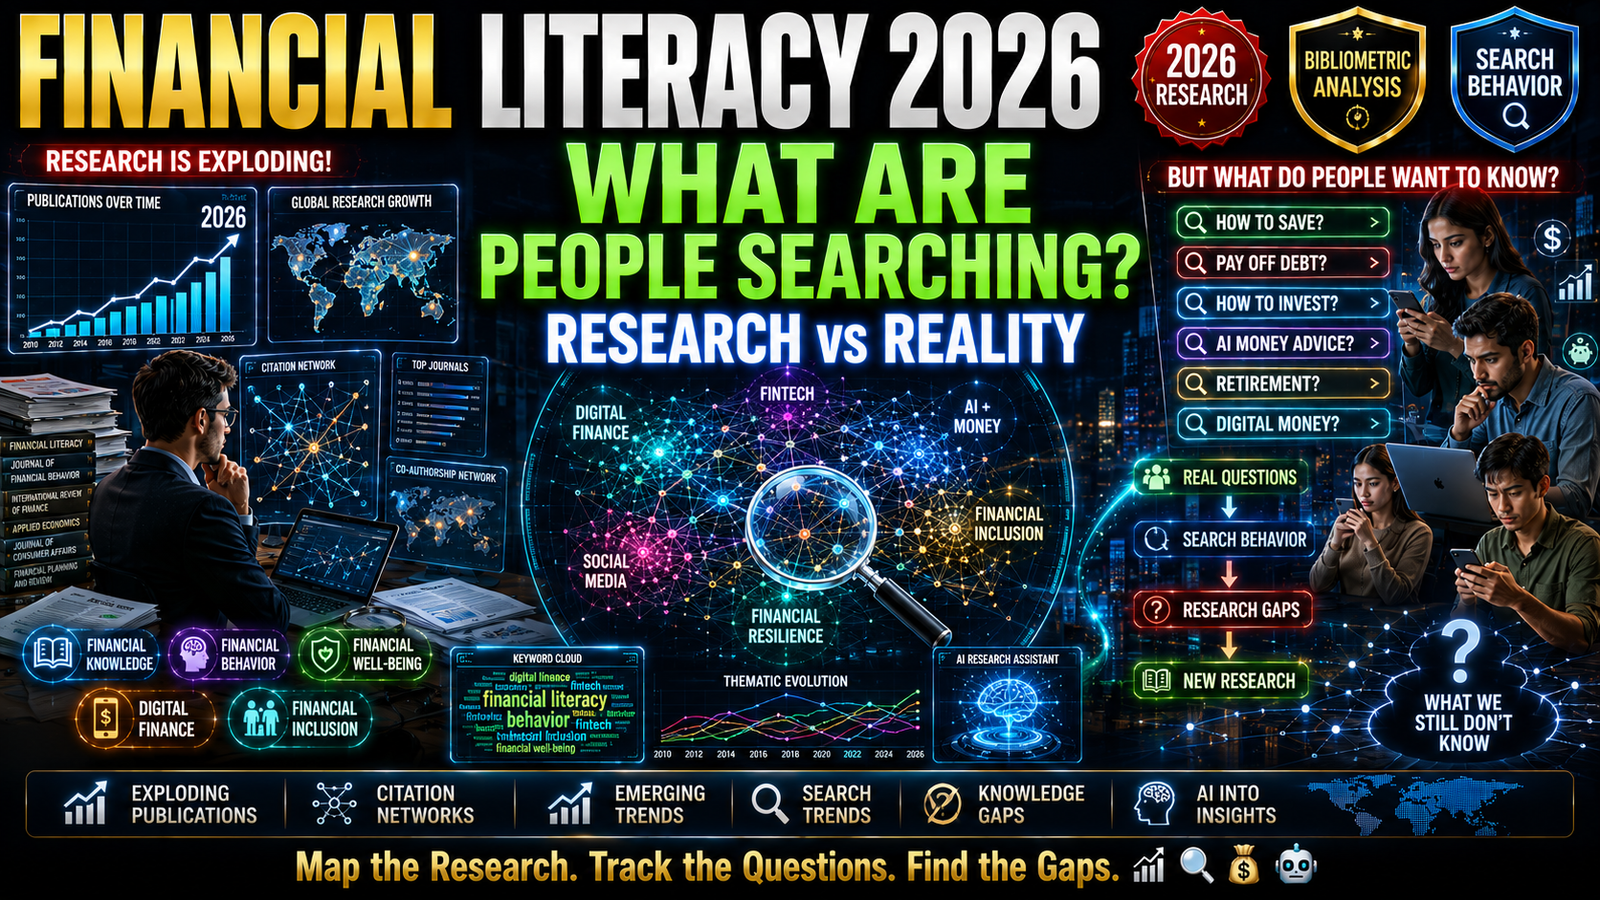
A comprehensive bibliometric analysis of financial literacy research, covering 970 Scopus-indexed journal articles published between 2008 and 2026, reveals a field that has expanded dramatically . The field is characterized by a rapidly expanding research domain, a high annual growth rate, and growing international engagement .
Another study analyzing 859 documents from 2010 to 2024 confirms this trend, noting a significant increase in publication output reflecting growing research community interest . Key journals driving the field include the Journal of Pension Economics and Finance, the International Journal of Bank Marketing, and Sustainability (Switzerland) .
Geographic and Institutional Leadership
The geographic distribution of financial literacy research has shifted dramatically:
- The United States remains the most cited and productive country with 278 publications and 1,758 total citations . It collaborates primarily with European countries and some Asian nations .
- Emerging economies are driving the most recent growth. India, Indonesia, and Pakistan have become major contributors post-2024, reflecting the growing importance of financial literacy in developing markets .
- Africa is emerging as a critical research frontier. A retrospective analysis of 336 Scopus-indexed publications on African financial literacy found that human development is a dominant research theme, with economics and business management emerging as a new focus area .
The Most Influential Research
Two specific works stand out in the co-citation network of financial literacy research:
- Fernandes D (2014) published in Management Science is the most cited research paper worldwide, with 1,029 total citations .
- Lusardi A (2014) sits at the center of the co-citation network, indicating it is a highly impactful and foundational article .
Lusardi’s work helped establish the “Big Three” questions—measuring understanding of interest rates, inflation, and risk diversification—that became the gold standard for financial literacy surveys.
KEY RESEARCH THEMES AND EVOLUTION
Thematic Analysis: Three Phases of Evolution
Bibliometric analysis of financial literacy and investment decision-making reveals three clear evolutionary phases :
- Conceptual Foundation Phase (pre-2020): Early research focused on defining financial literacy, establishing measurement tools, and understanding basic financial knowledge.
- Behavioral Finance Phase (2020-2024): Research shifted to understanding psychological factors, cognitive biases, and the behavioral dimensions of financial decision-making.
- Cognitive Process-Oriented Phase (post-2024): Current research integrates digital financial tools, mitigates cognitive biases, and focuses on wealth maximization .
Dominant and Underdeveloped Themes
A 2026 bibliometric analysis identified key thematic patterns :
Dominant motor themes (well-developed, driving the field):
- Financial technology (FinTech)
- Structural equation modelling (reflecting methodological advancement)
Foundational yet underdeveloped themes (important but requiring deeper theoretical integration):
- Financial literacy
- Financial inclusion
- Digital financial inclusion
The Paradigm Shift
The most significant finding is a clear paradigm shift from traditional financial knowledge toward digital financial capability . This reflects the growing importance of technological competencies in shaping financial behavior in an increasingly digitalized financial ecosystem.
Emerging Research Clusters
Current research clusters around three interconnected themes :
- Financial management and education: Adult education, financial management, numeracy, self-control
- Financial literacy and well-being: Financial capability, financial education, financial inclusion, gender differences
- Youth financial knowledge and sustainability: Financial systems, retirement planning, training, young populations
THE INTERSECTION OF DIGITAL FINANCE AND FINANCIAL LITERACY
The FinTech and Digital Inclusion Connection
The 2026 bibliometric analysis covering 2008-2026 identified FinTech and structural equation modelling as dominant motor themes . This reflects both the methodological advancement of the field and its growing focus on technology’s role in financial behavior .
Research shows a significant positive relationship between financial inclusion, financial literacy, and financial technology adoption . Using worldwide data, studies find a significant positive relation between the World Bank’s “Findex” measures (which track financial inclusion) and measures of financial literacy .
The Digital Fraud and Financial Literacy Intersection
A separate bibliometric analysis examining the intersection of digital fraud and financial literacy analyzed 523 journal articles published between 2015 and 2026. This research cluster connects digital-fraud terms—online scams, phishing, identity theft—with financial-literacy and prevention terms like fraud awareness, consumer protection, and digital financial literacy.
This intersection is critical in 2026. As financial services move increasingly online, financial literacy must include the ability to identify scams, protect personal information, and understand the risks of digital financial products.
SEARCH BEHAVIOR AS A FINANCIAL LITERACY MEASURE
The Search-Based Financial Awareness Index
A pioneering 2026 study demonstrates the potential of utilizing search-based data derived from internet search behavior to develop household finance measures . The research introduces a novel search-based financial awareness index derived from the Search Volume Index (SVI) from Google Trends .
Key findings include:
- The index measures individuals’ awareness of topics related to individual retirement accounts (IRAs) and their efforts to acquire relevant financial knowledge .
- Significant time-series and cross-sectional heterogeneity exists in financial awareness .
- Increased financial awareness is associated with greater IRA savings .
- The findings confirm the financial awareness index as a valid measure .
The Value of Search-Based Data
The study highlights the value of search-based data as a complement to traditional survey-based measures, offering a solution to data limitations in household finance research . The methodology can be readily extended to other areas of household finance, providing real-time, behavioral measures of financial literacy that surveys cannot capture.
Financial Information Search Behavior
Research on financial information search behavior examines how individuals acquire, assess, and utilize financial information to assist in decision-making . Key findings include:
- Both financial knowledge and personal involvement are positively associated with relying on knowledge and experience, trusting experts, and collecting additional information when making financial decisions .
- Information-gathering capacity and risk tolerance significantly mediate these relationships .
- Financial self-efficacy plays a limited role .
What Drives Financial Information Search?
A study on borrowing decisions found that financial literacy, perceived financial knowledge, educational attainment, and engaging the services of a financial professional are all positively associated with information search behavior among consumers . Critically, consumers from underserved groups, who would benefit most from better information search, were the least likely to use it .
UNDER-RESEARCHED AREAS AND FUTURE DIRECTIONS
Persistent Research Gaps
Bibliometric analyses consistently identify several critical research gaps :
- Behavioral dimensions remain under-explored, particularly the psychological factors that drive financial decision-making .
- Digital inclusion disparities require deeper investigation, especially how digital access and skills affect financial literacy .
- Regulatory frameworks for digital finance need more research attention .
Methodological Gaps
A Malaysian literature review identifies three persistent methodological gaps :
- Over-reliance on student samples
- Dominance of cross-sectional survey designs
- Limited use of theory-driven or longitudinal approaches
Emerging Research Questions for 2026 and Beyond
Based on the bibliometric evidence, future research should address:
- How does digital financial literacy differ from traditional financial literacy?
- What interventions effectively build digital financial capability?
- How can financial literacy programs address behavioral biases and cognitive errors?
- What role do AI and machine learning play in financial literacy and decision-making?
- How can financial education be delivered effectively in emerging economies?
FREQUENTLY ASKED QUESTIONS
What is bibliometric analysis in financial literacy?
Bibliometric analysis is a quantitative method that examines academic publications to reveal trends, influential contributors, key themes, and knowledge gaps in a research field. In financial literacy, bibliometric analysis has shown the field’s shift from basic measurement to digital and behavioral topics .
What are the most researched topics in financial literacy?
Current research focuses on financial inclusion, digital literacy, behavioral finance, financial well-being, and youth financial knowledge. The field has moved beyond the “Big Three” questions about interest rates, inflation, and risk diversification .
Who are the most influential researchers in financial literacy?
Professor Annamaria Lusardi is widely recognized as the most influential researcher, with her 2014 article sitting at the center of the co-citation network . Fernandes D (2014) is the most cited research paper, with over 1,000 citations .
Where is financial literacy research growing fastest?
Research output has grown exponentially since 2020, driven by digitalization and interest in FinTech . Emerging economies—particularly India, Indonesia, and Pakistan—are driving recent growth, while the United States remains the most productive country . Africa is an emerging frontier .
What is the connection between search behavior and financial literacy?
Search-based data from Google Trends can measure financial awareness in real time. A 2026 study found that increased financial awareness, measured through search patterns, is associated with greater retirement savings . Search-based data complements traditional survey-based measures .
How is digital finance changing financial literacy research?
Research is shifting from traditional financial knowledge toward digital financial capability, emphasizing the importance of technological competencies . FinTech has emerged as a dominant research theme, and digital financial inclusion is increasingly important .
What are the under-researched areas in financial literacy?
Key gaps include behavioral dimensions, digital inclusion disparities, regulatory frameworks, and methodological limitations such as over-reliance on student samples and cross-sectional designs .
CONCLUSION
Financial literacy research in 2026 reveals a field at a turning point. The evidence from academic publications and search data all points to the same conclusion: financial literacy is essential, yet understanding of it remains alarmingly low across populations.
The research landscape has shifted dramatically. The field has grown exponentially, with annual growth rates accelerating post-2020. The focus has moved from measuring basic knowledge to exploring digital financial literacy, behavioral economics, and financial inclusion. Emerging economies are driving the most recent growth, reflecting the globalization of financial curiosity and concern.
Three key takeaways emerge:
First, financial literacy research has evolved from a narrow academic pursuit into a multidisciplinary field with global policy relevance. The volume and impact of research have grown substantially, with influential scholars and journals shaping the agenda.
Second, the field is undergoing a paradigm shift from traditional financial knowledge toward digital financial capability. The role of FinTech and digital financial inclusion has become central to research.
Third, critical gaps remain. Behavioral dimensions, digital inclusion disparities, and regulatory frameworks are under-explored. Methodological weaknesses, including over-reliance on student samples and cross-sectional designs, limit the evidence base.
For researchers, the message is clear: the future of financial literacy research lies in interdisciplinary, longitudinal, and theory-driven approaches that address the behavioral, digital, and inclusion dimensions of financial decision-making. For educators, the implication is that financial literacy programs must adapt to the digital age.
The demand for accessible, trustworthy financial education has never been greater—and the opportunity to meet that demand has never been clearer.
Disclaimer: This content is for informational and educational purposes only and does not constitute professional financial advice. Financial literacy empowers decision-making but is not a substitute for professional guidance.