INTRODUCTION
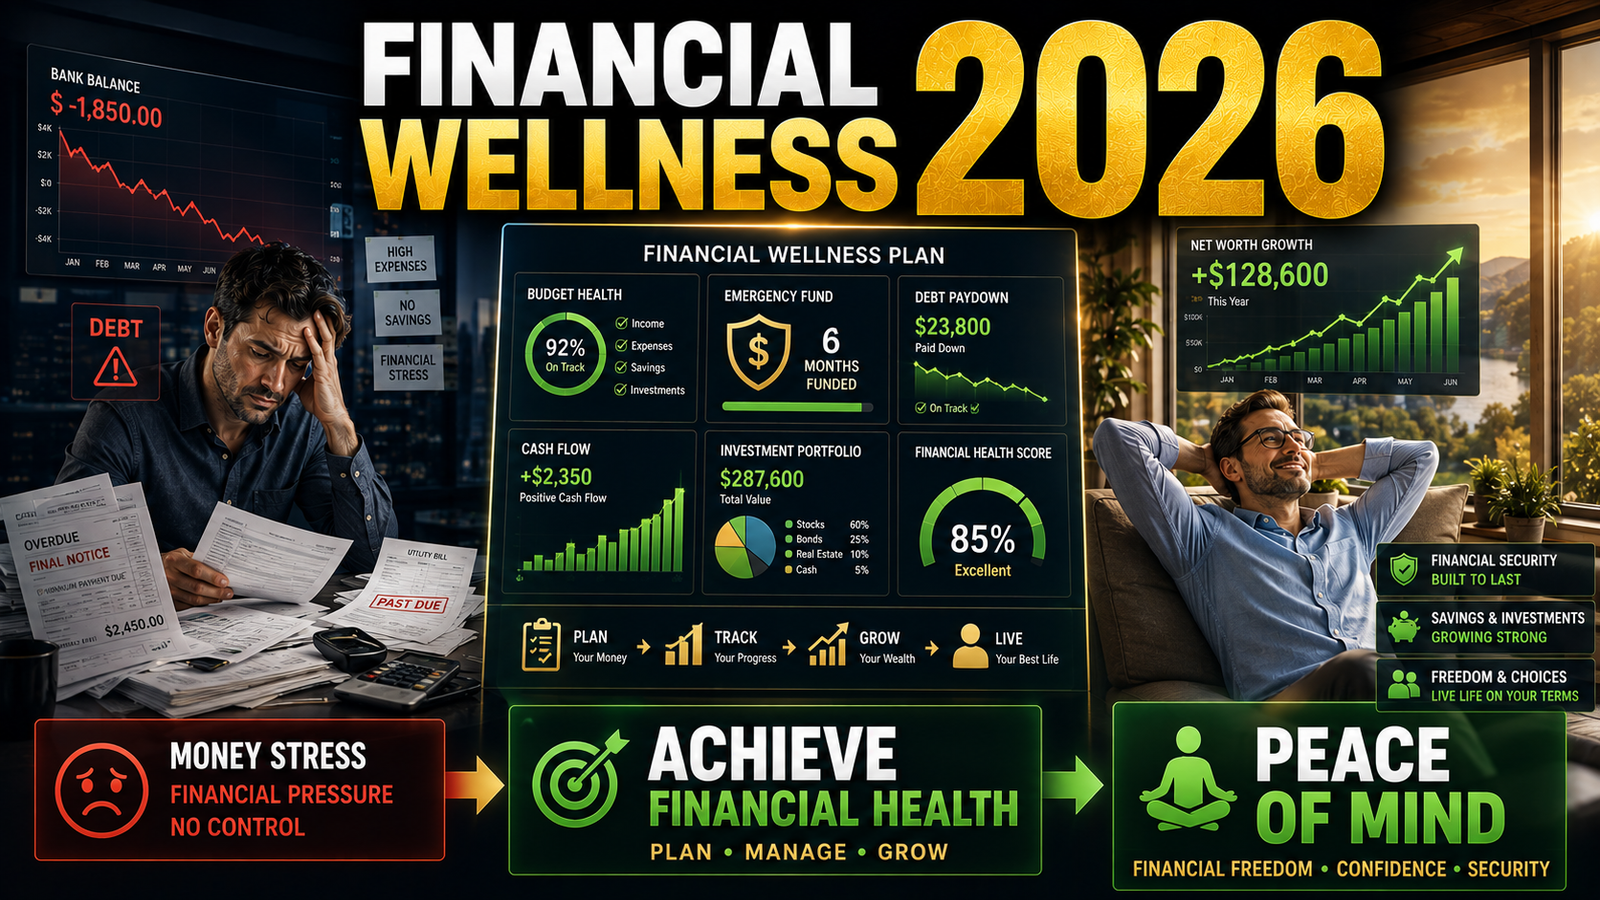
What does it truly mean to be financially well? For many, financial wellness is about more than just having money in the bank. It is about feeling in control of your finances, being able to absorb financial shocks, making progress toward your goals, and having the freedom to enjoy life without constant money-related stress.
According to PNC Bank’s Financial Wellness in the Workplace Report 2025, 67% of Americans report feeling financially stressed, and nearly 40% cannot afford an unexpected $400 expense. The situation is similar across many developed economies, with financial stress consistently ranking as a leading cause of anxiety, relationship problems, and reduced productivity.
In 2026, financial wellness has moved from a personal concern to a mainstream priority. Employers are increasingly offering financial wellness programs, governments are promoting financial literacy, and individuals are seeking education and tools to improve their financial health. The COVID-19 pandemic, inflation, and economic uncertainty have highlighted the importance of financial resilience.
In this complete guide, we will walk you through everything you need to know about financial wellness. You will learn what it means, why it matters, the key pillars of financial health, actionable strategies to improve your situation, common obstacles, and how to maintain long-term financial well-being. By the end, you will have a practical roadmap to achieve financial peace of mind.
WHAT IS FINANCIAL WELLNESS?
Financial wellness is the state of being in control of your financial life, feeling secure about your financial future, and having the ability to make choices that allow you to enjoy life. It is not just about how much money you have, but how you manage, protect, and grow your financial resources.
The Consumer Financial Protection Bureau (CFPB) defines financial well-being as “a state of being wherein a person can fully meet current and ongoing financial obligations, can feel secure in their financial future, and is able to make choices that allow them to enjoy life.”
Key dimensions of financial wellness include:
- Control over day-to-day finances: Managing cash flow, paying bills on time, and avoiding financial chaos
- Capacity to absorb financial shocks: Having savings and insurance to handle unexpected expenses
- Progress toward financial goals: Making consistent progress toward short-term and long-term objectives
- Financial freedom: Having the flexibility to make choices that enhance quality of life
- Peace of mind: Low financial stress and confidence in your financial future
Financial wellness is not a fixed destination but a continuous journey. It involves ongoing learning, adaptation, and intentional decision-making.
WHY FINANCIAL WELLNESS MATTERS IN 2026
Financial wellness has become increasingly important in 2026 for several compelling reasons.
Rising Cost of Living
Inflation and rising costs for housing, healthcare, education, and food are putting pressure on household budgets. Financial wellness provides the resilience needed to navigate these pressures without falling into debt or financial distress.
Economic Uncertainty
Global economic volatility, geopolitical tensions, and market fluctuations create financial anxiety. Financially well individuals are better equipped to weather economic storms and adapt to changing circumstances.
Mental and Physical Health Connection
Financial stress is a significant contributor to mental health issues, including anxiety and depression. It also affects physical health through stress-related conditions. Improving financial wellness improves overall well-being.
Changing Employment Landscape
The gig economy, remote work, and non-traditional employment arrangements have made traditional employer-provided benefits less reliable. Individuals must take greater responsibility for their financial security.
Aging Population and Retirement
With longer life expectancies and uncertain social security systems, individuals must plan for longer retirements. Financial wellness includes preparing for a secure retirement.
Employer Focus
Employers increasingly recognize that financially stressed employees are less productive and more likely to leave. Financial wellness programs have become a key part of employee benefits packages.
THE PILLARS OF FINANCIAL WELLNESS
Financial wellness rests on several interconnected pillars. Strengthening each pillar builds a solid foundation for financial health.
Pillar 1: Financial Literacy
Financial literacy is the understanding of basic financial concepts, including budgeting, saving, investing, debt management, and risk protection. Without financial literacy, it is difficult to make informed decisions. Key areas include:
- Understanding interest rates and compounding
- Knowing the difference between assets and liabilities
- Recognizing good debt versus bad debt
- Understanding investment basics, including risk and return
- Knowing how taxes work
Pillar 2: Cash Flow Management
Cash flow management involves tracking income and expenses to ensure you live within your means. This is the foundation of financial health. Key practices include:
- Creating and maintaining a budget
- Tracking spending habits
- Differentiating between needs and wants
- Reducing unnecessary expenses
- Living below your income level
Pillar 3: Emergency Savings
An emergency fund provides a financial buffer against unexpected expenses, such as medical emergencies, car repairs, job loss, or home maintenance. Financial experts recommend three to six months’ worth of living expenses.
Pillar 4: Debt Management
Managing debt effectively is crucial for financial wellness. This involves:
- Avoiding high-interest debt
- Prioritizing debt repayment
- Using debt strategically for education, housing, or business
- Understanding the cost of debt through interest rates and fees
Pillar 5: Investment and Wealth Building
Building wealth requires investing in assets that grow over time. This includes:
- Retirement accounts (401(k), IRA, pensions)
- Stock market investments (ETFs, mutual funds, individual stocks)
- Real estate
- Business ownership
- Other appreciating assets
Pillar 6: Risk Management and Insurance
Protecting your financial well-being requires adequate insurance coverage. This includes:
- Health insurance
- Life insurance
- Disability insurance
- Home and auto insurance
- Umbrella liability coverage
Pillar 7: Goal Setting and Planning
Financial wellness requires clear goals and a plan to achieve them. This includes short-term goals (saving for a vacation), medium-term goals (buying a home), and long-term goals (retirement).
HOW TO IMPROVE YOUR FINANCIAL WELLNESS – STEP BY STEP
Improving financial wellness is a gradual process. Follow these steps to build a healthier financial life.
Step 1: Assess Your Current Financial Situation
Start by taking an honest look at your finances. Gather information about:
- Your total income (after tax)
- Your total expenses (fixed, variable, discretionary)
- Your assets (savings, investments, property)
- Your liabilities (debts, loans, mortgages)
- Your net worth (assets minus liabilities)
- Your credit score
Step 2: Create a Realistic Budget
Develop a budget that aligns with your income, expenses, and goals. The 50/30/20 rule is a simple starting point:
- 50% of income for needs (housing, utilities, food, transportation, minimum debt payments)
- 30% for wants (entertainment, dining out, hobbies, vacations)
- 20% for savings and debt repayment (emergency fund, retirement, extra debt payments)
Step 3: Build an Emergency Fund
Start saving for emergencies. Aim to set aside three to six months of essential living expenses. Begin by saving a small amount each month and gradually increase it. Consider keeping these funds in a separate, easily accessible account.
Step 4: Pay Down High-Interest Debt
Prioritize paying off high-interest debt, such as credit cards, personal loans, and payday loans. Strategies include:
- The debt snowball method (pay smallest balances first)
- The debt avalanche method (pay highest interest rates first)
- Debt consolidation (combining debts at a lower interest rate)
Step 5: Start Investing for the Future
Once you have an emergency fund and have managed high-interest debt, begin investing. If your employer offers a 401(k) match, contribute enough to receive the full match. Consider opening an IRA or investing in low-cost index funds.
Step 6: Protect Your Financial Health
Ensure you have adequate insurance coverage. Review your health, life, disability, home, and auto insurance policies annually. Consider increasing coverage if your situation has changed.
Step 7: Set Financial Goals
Define clear, specific, and realistic financial goals. Examples include:
- Save $10,000 for a home down payment in 3 years
- Pay off credit card debt within 18 months
- Increase retirement savings to 15% of income within 2 years
- Build an emergency fund of $15,000 within 12 months
Step 8: Review and Adjust Regularly
Financial wellness is an ongoing process. Review your budget, goals, and progress monthly or quarterly. Adjust your plan as your circumstances change.
COMMON OBSTACLES TO FINANCIAL WELLNESS
Understanding obstacles helps you overcome them. Common barriers include:
Lack of Financial Education
Many people lack basic financial literacy, making it difficult to make informed decisions. Education is the first step toward improvement.
Low Income
Limited income makes it challenging to save and invest. Focus on building skills, advancing your career, or finding additional income streams.
High Debt Burden
Debt payments consume a significant portion of income, leaving little room for savings. Prioritize debt reduction and avoid new high-interest debt.
Lifestyle Inflation
As income increases, expenses often rise proportionally. Avoid lifestyle inflation by saving any increase in income rather than spending it.
Emotional Spending
Stress, boredom, and social pressure can lead to emotional spending. Develop awareness of your spending triggers and find healthier coping mechanisms.
Lack of Support
Financial wellness is harder without support. Join financial education groups, work with a financial coach, or involve family members in your financial journey.
Unexpected Life Events
Job loss, medical emergencies, divorce, and other events can derail financial plans. Build resilience through emergency savings and insurance.
THE ROLE OF EMPLOYERS IN FINANCIAL WELLNESS
Employers play an increasingly important role in supporting financial wellness.
Financial Wellness Programs
Many employers now offer financial wellness programs that include education, coaching, and tools. These programs can improve employee financial health and productivity.
Employer-Sponsored Retirement Plans
401(k) plans with employer matching are powerful tools for building retirement savings. Encourage employees to contribute and take full advantage of matches.
Financial Education Workshops
Workshops on budgeting, investing, and debt management help employees improve financial literacy. These can be offered in-person or online.
Access to Financial Advisors
Some employers provide access to financial advisors or counseling services. This can help employees navigate complex financial decisions.
Emergency Savings Programs
Innovative employers are offering emergency savings accounts, payroll deductions for savings, and matching contributions to emergency funds.
THE PSYCHOLOGY OF FINANCIAL WELLNESS
Financial wellness is not just about numbers; it is also about mindset and behavior.
Money Mindset
Your beliefs about money shape your financial behavior. A scarcity mindset can lead to anxiety and hoarding, while an abundance mindset can lead to overspending. Developing a balanced, healthy money mindset is essential.
Behavioral Finance
Understanding behavioral biases, such as loss aversion, overconfidence, and present bias, helps you make better financial decisions. Being aware of these biases can help you avoid costly mistakes.
Financial Stress and Mental Health
Financial stress is a major contributor to anxiety, depression, and relationship problems. Addressing financial issues can significantly improve mental health and overall well-being.
The Power of Habits
Financial wellness is built through habits. Small, consistent actions – like tracking expenses, saving automatically, and reviewing your budget – compound over time.
Delayed Gratification
The ability to delay gratification is a key predictor of financial success. Practice prioritizing long-term goals over short-term desires.
FINANCIAL WELLNESS AT DIFFERENT LIFE STAGES
Financial wellness looks different at different stages of life.
Early Career (20s to 30s)
Focus on building financial literacy, creating a budget, establishing an emergency fund, starting retirement savings, and avoiding high-interest debt. This is the time to build good habits.
Mid-Career (30s to 50s)
Focus on increasing savings, paying down debt, investing for growth, protecting assets through insurance, and planning for major expenses like education and home purchases.
Pre-Retirement (50s to 60s)
Focus on maximizing retirement contributions, reducing debt, reviewing asset allocation, and planning for retirement income and healthcare costs.
Retirement (60s and Beyond)
Focus on managing retirement income, preserving capital, managing taxes, maintaining insurance coverage, and estate planning.
FREQUENTLY ASKED QUESTIONS
What is financial wellness?
Financial wellness is a state of being in control of your finances, feeling secure about your future, and having the freedom to make choices that improve your quality of life.
How can I improve my financial wellness?
Start by assessing your financial situation, creating a budget, building an emergency fund, paying down debt, investing for the future, and setting clear financial goals.
What is the 50/30/20 rule?
The 50/30/20 rule is a simple budgeting framework where 50% of income goes to needs, 30% to wants, and 20% to savings and debt repayment.
How much should I have in an emergency fund?
Financial experts recommend three to six months’ worth of living expenses. Start with a smaller goal, such as $1,000, and gradually build up.
What are the biggest obstacles to financial wellness?
Common obstacles include low income, high debt, lack of financial education, lifestyle inflation, emotional spending, and unexpected life events.
Why do employers care about financial wellness?
Financially stressed employees are less productive, more likely to call in sick, and more likely to leave. Financial wellness programs benefit both employees and employers.
Is financial wellness only about money?
No. Financial wellness also includes financial literacy, emotional well-being, goal achievement, and peace of mind.
CONCLUSION
Financial wellness is essential for a happy, healthy, and secure life. It is not about being rich – it is about having control over your finances, feeling confident about your future, and being able to enjoy life without constant financial stress.
Improving financial wellness is a journey, not a destination. It starts with education, followed by intentional actions like budgeting, saving, investing, and protecting your assets. Small, consistent steps over time lead to significant progress. Be patient with yourself and celebrate small wins along the way.
In 2026, financial wellness has become more accessible than ever. With free online resources, employer programs, fintech tools, and a growing focus on financial literacy, everyone can improve their financial health. Take the first step today – your future self will thank you.
Explore more financial wellness and personal finance guides on Akashhelps.com.
Disclaimer: This content is for informational and educational purposes only and does not constitute professional financial advice. Always consult with a qualified financial advisor or planner regarding your specific financial situation. Akashhelps.com is not responsible for any losses or damages resulting from the use of this information.
Author Bio: This guide was written by the finance content team at Akashhelps.com, with expertise in personal finance, financial planning, and financial education. We are committed to providing accessible, accurate, and actionable financial guidance.
Last reviewed: August 2026
Sources:
- Consumer Financial Protection Bureau – Financial Well-Being Framework
- PNC Bank – Financial Wellness in the Workplace Report 2025
- Empower Research – Emergency Savings Report
- American Psychological Association – Financial Stress and Mental Health
- Voya – 2026 Financial Wellness Calendar